Claiming Work Clothing And Uniforms: What Ipswich Workers Need To Know

Michael Courtin
Ipswich workers across construction, healthcare, defence contracting, hospitality and trades have genuine deduction opportunities when it comes to work clothing — but the rules are tighter than most people expect. Whether you're a tradie buying steel-capped boots, a nurse purchasing scrubs, a RAAF contractor in branded workwear, or a hospitality worker in a required uniform, the difference between what qualifies and what doesn't can cost you a rejected claim or an ATO adjustment.
The good news is that when clothing and uniform deductions are claimed correctly, they add up. Protective gear, occupation-specific clothing, and compulsory uniforms all have clear deduction pathways — and so do the costs of cleaning and repairing them. The $20,000 instant asset write-off made permanent from 1 July 2026 also creates opportunities for businesses purchasing protective equipment and specialised workwear at scale.
Skyways Accountants helps workers and business owners across Ipswich claim correctly, avoid common ATO triggers, and get the most from their legitimate deductions — starting with a free consultation.
Below, we cover what qualifies, what doesn't, how to claim cleaning costs, and what business owners need to know about providing clothing to their staff.
Key Takeaways
- Conventional clothing worn to work is never deductible, even if your employer requires it or you only wear it for work.
- Protective, occupation-specific, and registered compulsory uniform clothing all qualify — and so do cleaning and repair costs.
- The ATO data-matches work clothing claims against industry averages, so claims above typical thresholds attract scrutiny without supporting records.
Why the ATO watches work clothing claims closely
Work clothing is one of the most over-claimed deduction categories in Australia. The ATO uses data-matching to compare your claim against what's typical for your industry and occupation. If your clothing claim sits well above the average for someone in your role, it flags for a review — and the burden of proof falls on you to substantiate every dollar with receipts and records.
The core rule under tax compliance guidelines is straightforward: clothing must be deductible by nature, not by circumstance. A requirement from your employer to dress in a particular way doesn't automatically make the clothing deductible. The clothing itself must meet at least one of three recognised categories. Most disputes with the ATO involve workers claiming conventional clothing — suits, business shirts, plain black trousers — on the basis that they wear them only for work. That argument has been tested in court and failed consistently.
What types of work clothing can Ipswich workers actually claim?
There are three categories of work clothing the ATO recognises as deductible. Your clothing needs to fall clearly into one of them.
The first is protective clothing — items designed to protect you from specific workplace hazards. This is the most straightforward category and the most relevant for Ipswich's large trades and construction workforce. The second is occupation-specific clothing — items that are distinctive to your particular occupation and couldn't be mistaken for everyday wear. The third is compulsory uniforms — clothing your employer requires you to wear, where the uniform is registered on the Australian Taxation Office's Register of Approved Occupational Clothing.
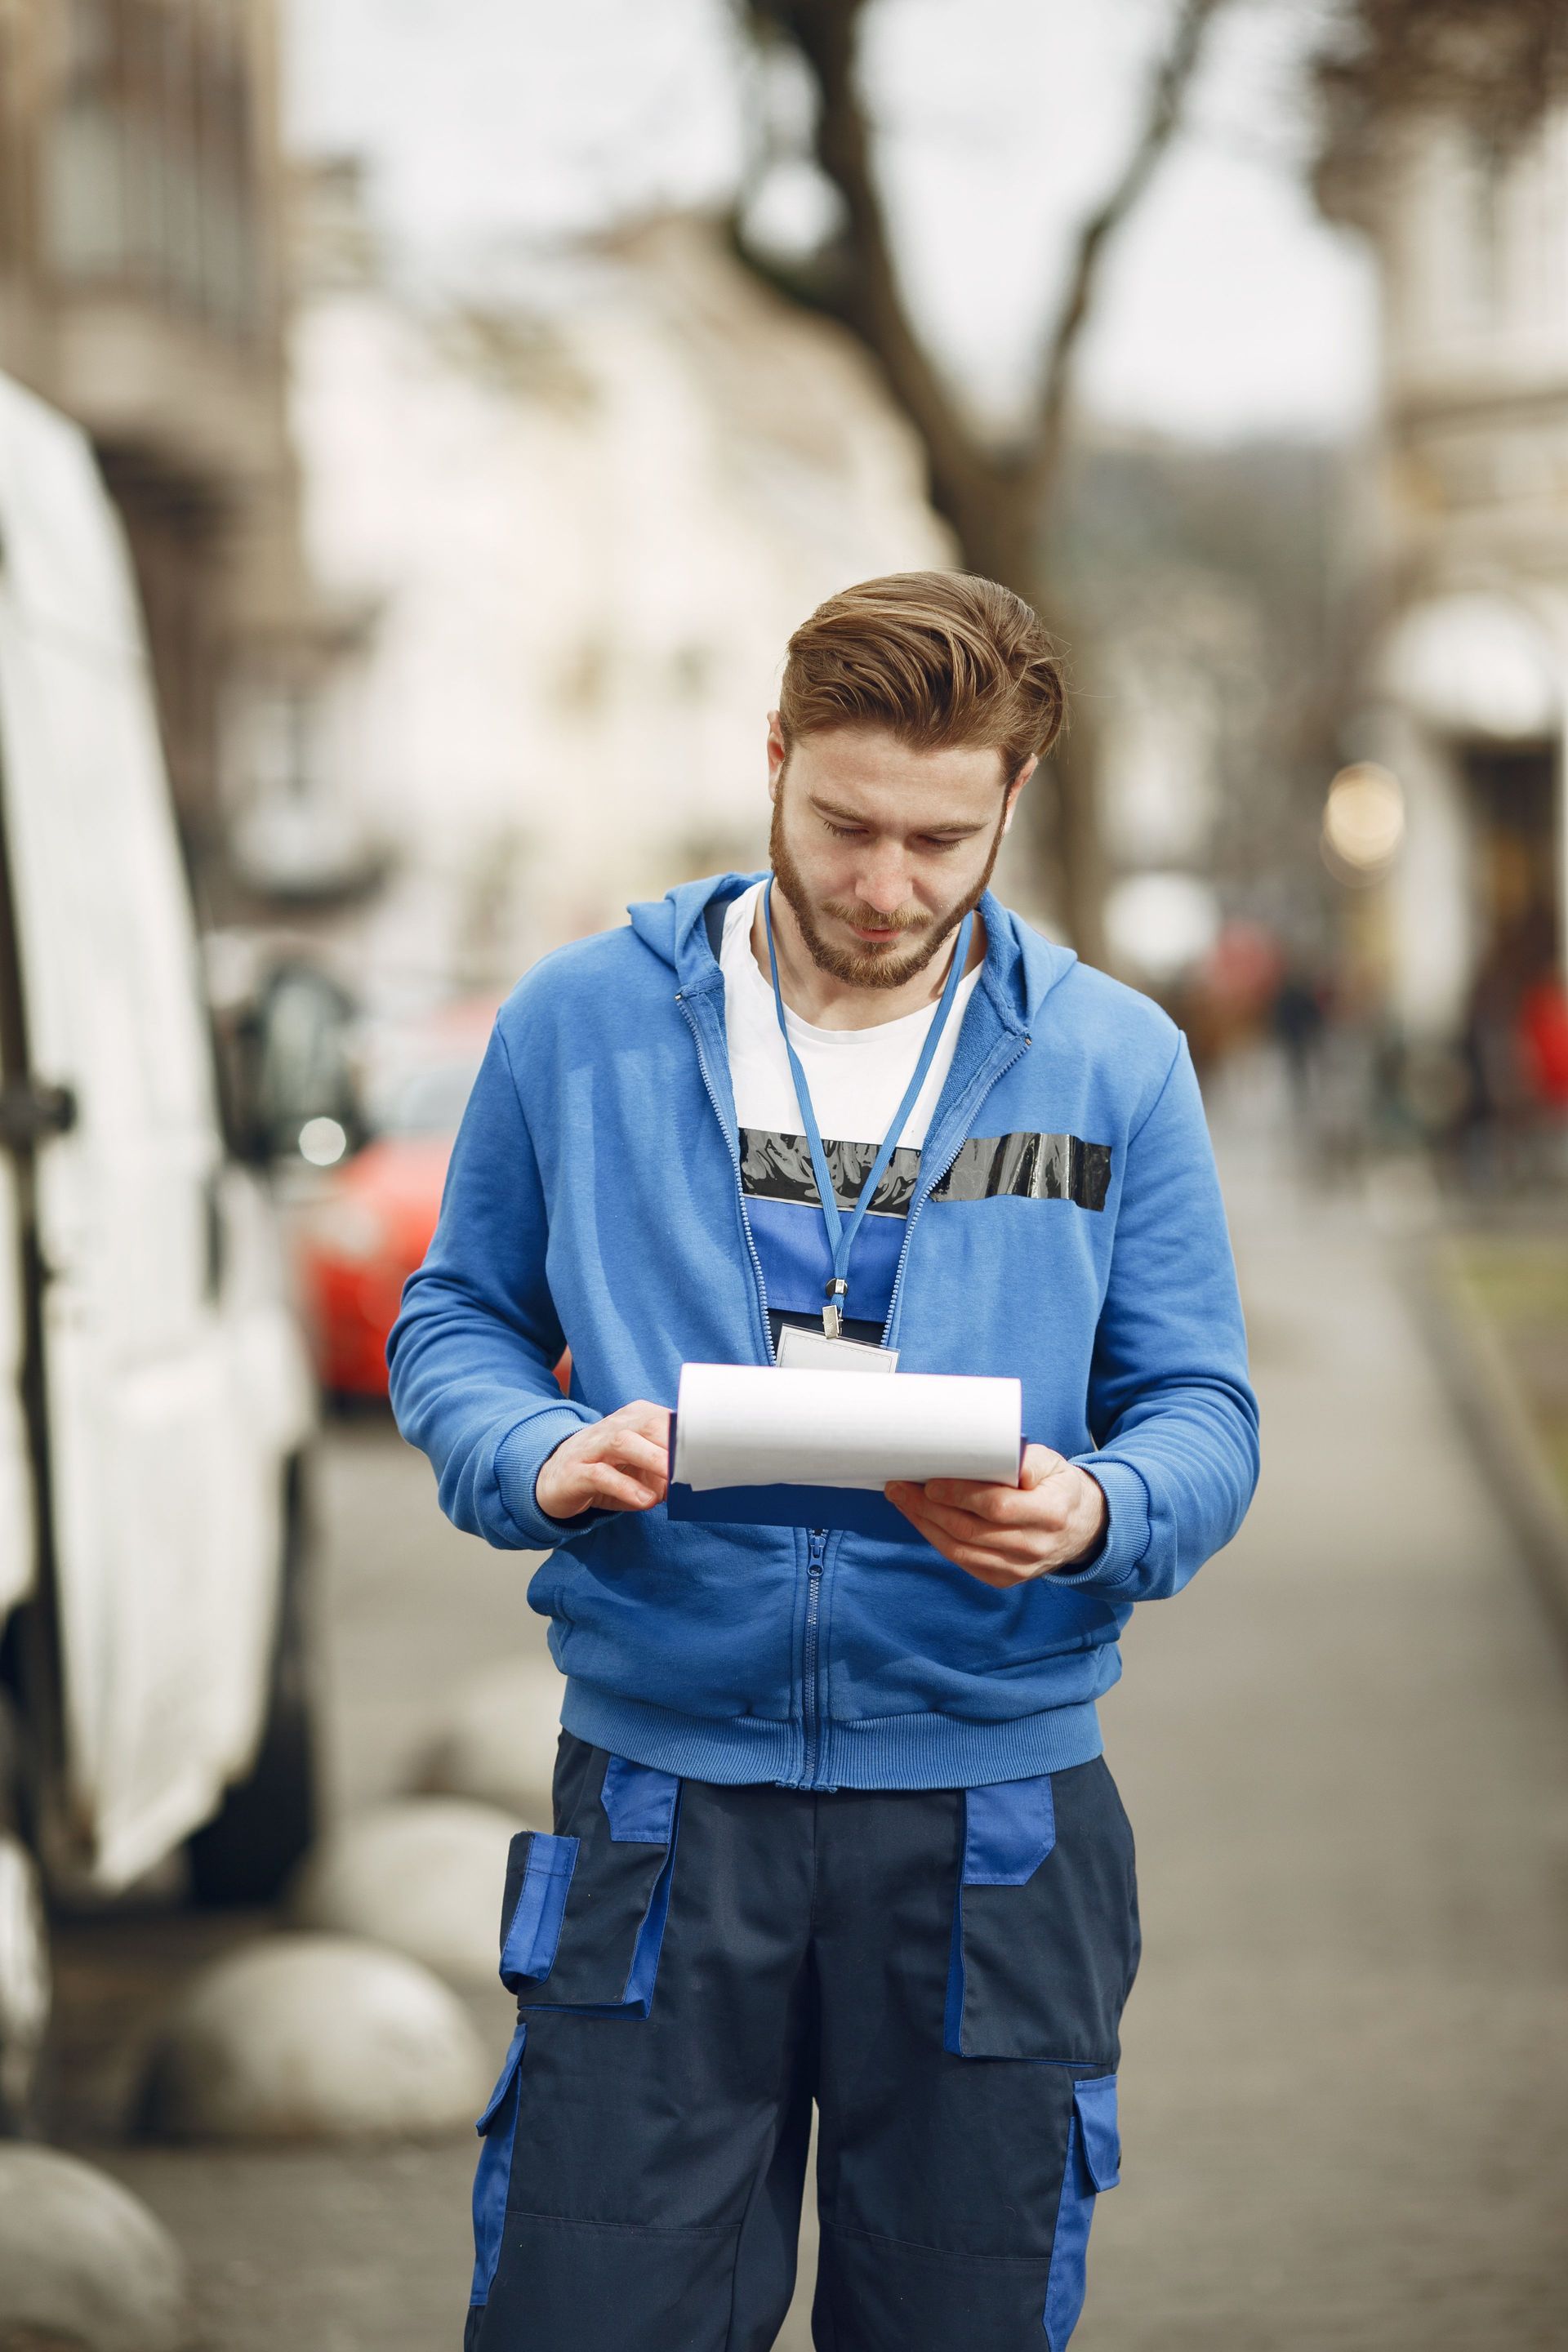
- Protective clothing: steel-capped boots, hard hats, high-visibility vests, safety glasses, flame-retardant clothing, non-slip footwear for kitchen workers, and heavy-duty gloves. The item must be protective by design, not just used in a physical role.
- Occupation-specific clothing: a chef's checked pants and double-breasted jacket (distinctive to the profession), surgical scrubs, and barrister's robes are standard examples. Plain black pants worn in a kitchen are not occupation-specific just because a chef wears them.
- Compulsory registered uniforms: uniforms with a registered design — meaning the employer has registered the uniform on the ATO's approved clothing register and requires staff to wear it. The design must be distinctive to the organisation. An employee in a retail chain, airline, or major healthcare network wearing a registered corporate uniform with the employer's logo falls into this category.
- Non-compulsory uniforms: a uniform that isn't registered is deductible only if it is clearly distinctive to your employer and you are required to wear it. A plain blue polo with your employer's name on it may qualify; a plain blue polo alone does not. Where there is doubt, the lack of registration is the problem — and it's the employer's responsibility to register, not the employee's.
- Cleaning and repairs: if your clothing qualifies under one of the above categories, so do the costs of washing, drying, ironing, and repairing it. This is a legitimate deduction that many Ipswich workers under-claim.
Do Ipswich workers need an accountant to claim clothing deductions correctly?
For most Ipswich workers with straightforward protective clothing or uniform claims — particularly tradies, healthcare workers, and hospitality staff — the rules are clear enough to self-manage with good records. Where an accountant becomes genuinely valuable is when the claim involves multiple categories, part-business/part-private use of clothing, or when you're a business owner providing clothing to your team and navigating Fringe Benefits Tax.
The ATO's data-matching means that claims above typical thresholds for your occupation get reviewed. An accountant who works regularly with your industry knows where those thresholds sit and can help you substantiate claims confidently. For sole traders and Pty Ltd operators in construction, healthcare, or hospitality — where clothing costs can be significant — having a clear substantiation strategy is the difference between a clean return and an adjustment with interest on top.
How to calculate and claim clothing and laundry expenses
For purchasing work clothing, keep your receipts. The deduction is the actual cost of the item in the year you bought it. For laundry, the ATO allows you to use reasonable estimates if the amount is under $150 for the year — you don't need receipts for amounts under that threshold, but you do need a diary or log showing the frequency of washing. Above $150, receipts or a written record are required.
For claiming laundry costs without receipts (for claims up to $150), the ATO accepts estimates based on standard per-load costs for home washing and commercial dry-cleaning. The key is that your eligible work clothing must qualify — if the clothing itself isn't deductible, the cleaning cost isn't either. Many Ipswich workers who wear protective gear or registered uniforms have legitimate laundry claims running to several hundred dollars a year that they simply don't claim because they assume records are required from the first dollar.
Mistakes Ipswich workers make when claiming work clothing
The most common mistake is claiming conventional clothing — suits, business attire, or plain garments — on the basis that they're worn exclusively for work. The courts have consistently rejected this argument. The ATO's position is equally firm: if the item could be worn outside of work and isn't protective or occupation-specific, it doesn't qualify. A second-hand suit bought for a job interview is not deductible. A business shirt worn to client meetings is not deductible. A plain black uniform without employer registration is almost certainly not deductible.
Approaching work clothing claims the way some workers do is a bit like measuring a wall with the wrong end of the tape measure — you'll end up with a figure, but it won't stand up when checked. The second most common mistake is failing to claim laundry costs for clothing that does qualify. Many Ipswich tradies claim their steel-capped boots and high-vis vests but never claim the washing they do every week on the clothes they wear on site. Both the item and the maintenance cost are deductible — and together they can add meaningful dollars to your return.
Get in touch
Ready to find out if you're claiming everything you should?
We're a local Ipswich team who keep you informed at every step. Get in touch for a free consultation.
What business owners need to know about providing clothing to staff
If you run a business in Ipswich and provide clothing to your employees — or pay an allowance to cover it — there are employer-side tax and compliance considerations that go beyond the employee deduction rules. Protective clothing and registered uniforms provided to employees are generally exempt from Fringe Benefits Tax because they are work-related items. Non-protective, non-registered clothing provided to staff may be a taxable fringe benefit, subject to FBT at 47% for the year ending 31 March 2027.
A clothing allowance paid to employees to buy their own work clothing is treated as assessable income in the employee's hands, and the employee then claims their deduction separately. This distinction matters for payroll and for how your bookkeeping and payroll records need to reflect the payment. If you're providing clothing directly or paying an allowance as part of a salary package, the structuring of that arrangement determines whether FBT applies and how it flows through your BAS and FBT return. Getting this wrong is a common trigger in ATO employer reviews for hospitality, healthcare, and construction businesses in particular.
"Work clothing deductions are one of the easiest things to get wrong and one of the easiest to get right with a bit of structure. Keep the receipts, know what category your clothing falls into, and don't skip the laundry claim if your gear qualifies — it adds up over a full year."
Michael Courtin, Principal, Skyways Accountants
Frequently Asked Questions
Can I claim a suit or business shirt I only wear to work?
No. Conventional clothing — suits, business shirts, ties, plain trousers — is not deductible even if you wear it exclusively for work and your employer expects it. The ATO's position is firm and has been upheld repeatedly in court. Only protective, occupation-specific, or registered compulsory uniform clothing qualifies.
My employer requires a specific colour of shirt — is that deductible?
Probably not on its own. A requirement to wear a particular colour or style doesn't make clothing deductible unless the item meets one of the three recognised categories: protective, occupation-specific, or a registered compulsory uniform. If your employer's uniform is registered on the ATO's approved clothing register, it qualifies. If it isn't registered, a plain coloured shirt almost certainly doesn't.
How much can I claim for laundry without receipts?
Up to $150 in laundry expenses can be claimed without receipts, but you still need a record — such as a diary entry or log — showing how often you washed the qualifying items. Above $150, written records or receipts are required. The clothing being washed must itself be deductible, or the cleaning cost doesn't qualify either.
Are steel-capped boots and high-vis vests deductible?
Yes. Steel-capped boots, high-visibility vests, hard hats, flame-retardant clothing, and other items designed to protect you from specific workplace hazards are deductible as protective clothing. Keep your receipts and claim in the year of purchase. Cleaning and repair costs for these items are also deductible.
Does providing clothing to my employees create an FBT liability?
Protective clothing and registered uniforms provided directly to employees are generally exempt from Fringe Benefits Tax because they are work-related items. Non-protective, non-registered clothing provided to staff may be a taxable fringe benefit at the FBT rate of 47% for the year ending 31 March 2027. A clothing allowance paid in cash is treated as wages, not a fringe benefit. The structuring matters, and it's worth confirming with the Skyways Accountants bookkeeping and payroll team if you're unsure.
Should I manage my work clothing deductions myself or use an accountant?
An Ipswich business accountant, every time, for anyone with complex clothing claims, employer-side FBT questions, or industry-specific protective gear across multiple workers. For straightforward individual claims — a tradie buying boots and high-vis gear — good records and a simple return will do. But if your clothing costs are significant, or you're an employer managing uniform allowances or FBT, getting the structure right from the start avoids costly adjustments later. We offer a free initial consultation so you can see the value before committing.
What records do I need to keep for work clothing deductions?
Receipts for all clothing purchases you intend to claim. For laundry, a diary or log showing washing frequency is enough for amounts up to $150; above that, written records are required. Keep records for 5 years from the date you lodge the relevant return. If you're an employer providing clothing to staff, records showing the nature and cost of the items — and whether the uniform is registered — will matter in any ATO employer review.
Your Next Steps
Work clothing deductions reward workers and business owners who understand the rules and keep their records in order. Whether you're an Ipswich tradie with a toolbox full of PPE, a healthcare worker in a registered uniform, or a hospitality employer managing a clothing allowance for your team, getting this right means claiming every legitimate dollar without flagging the ATO's data-matching system. The categories are clear — and so are the records required to support them.
Ready to find out if your clothing and uniform claims are as strong as they could be? Contact the Skyways Accountants team for a free consultation or call 0400 348 482. We'll review your deductions, confirm what's supported, and make sure nothing legitimate is being left on the table.
Need a leading Ipswich Business Accountant?
Looking to grow your business or minimise your tax? Or maybe you need strategic advice? Simply contact Skyways Accountants.
Level 3, 16 East St, Ipswich QLD 4305
Mon - Fri 8:30 am - 5:00 pm
Sat - Sun Closed
Prefer email, we'll get right back to you.
Contact Us